
Finance Guides for Cutting Daily Expenses
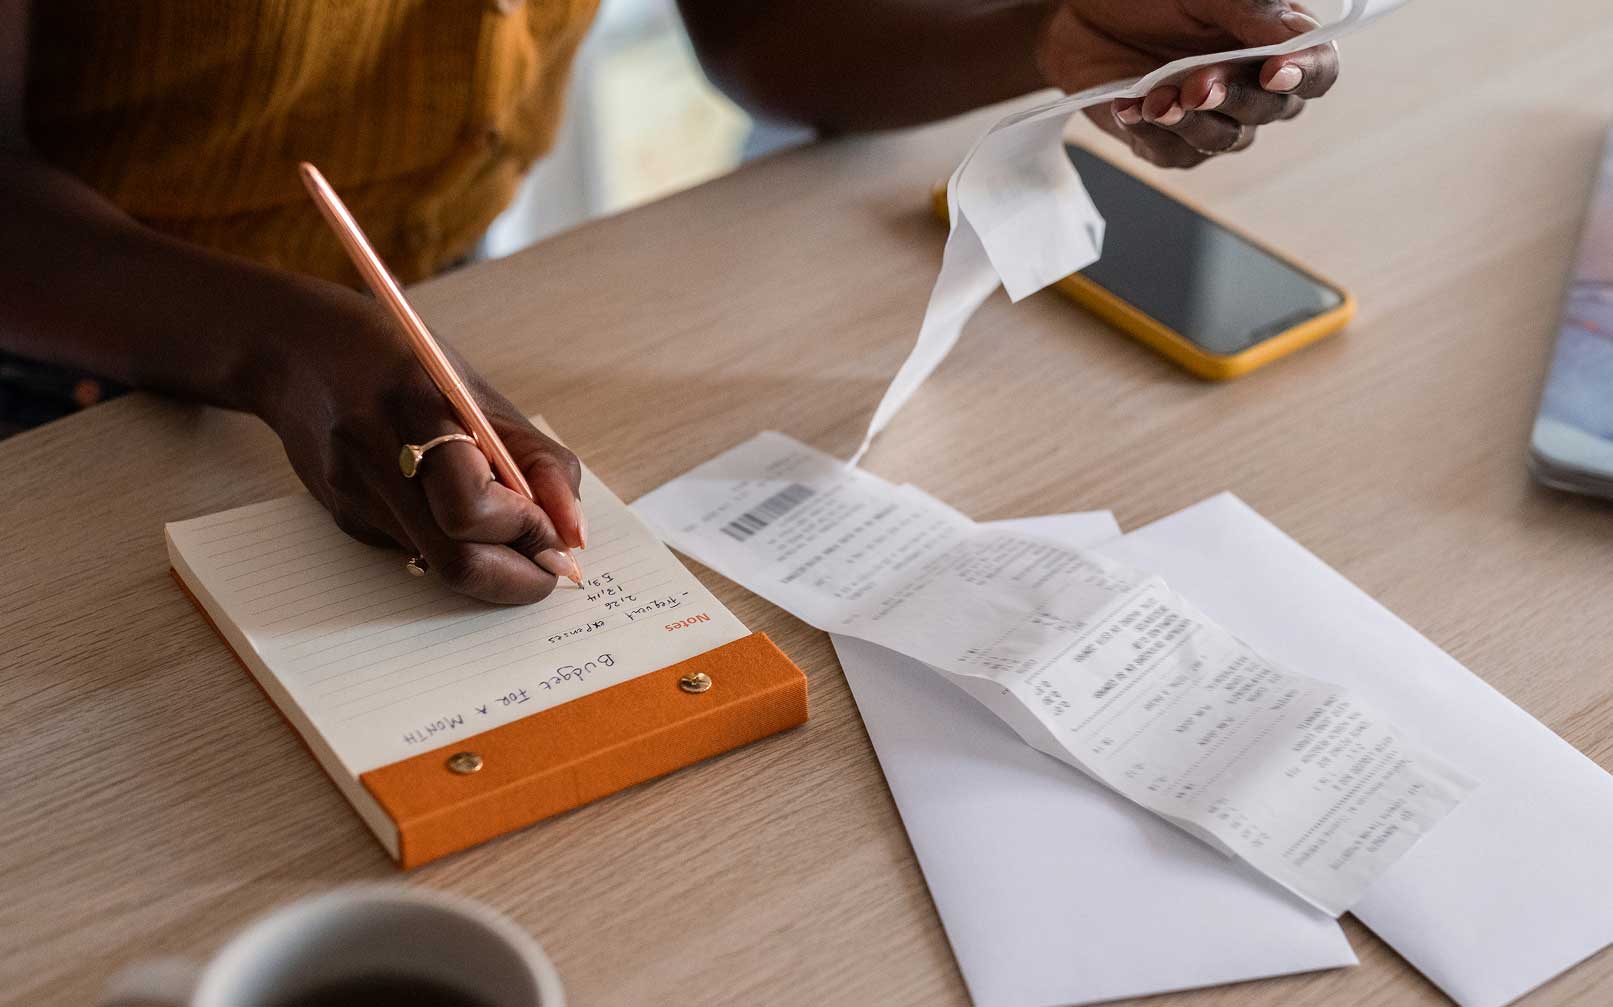
The pursuit of economical living begins with deliberate planning and a willingness to inspect personal habits from a fresh perspective. Many individuals aspire to reduce everyday costs but often overlook small patterns that gradually drain funds. Understanding these principles can transform casual decision making into a structured financial strategy. The concept of cut daily expenses becomes more impactful when applied with consistent intention, helping households retain more of their hard earned income without sacrificing essential needs.
Understanding the Architecture of Everyday Spending
Daily expenditures often appear harmless in isolation. A modest beverage, a subscription renewal, or spontaneous shopping may seem insignificant. Yet when compiled over weeks or months, these expenditures reveal a pattern capable of undermining long term financial health. To navigate this effectively, it helps to map expenditures into distinct categories. Food, utilities, transportation, leisure, and personal services all form a mosaic that influences the overall financial equilibrium.
This categorization serves a dual purpose. It clarifies where money is being allocated and exposes areas where refinement is possible. Small shifts in routine can yield noticeable savings. For instance, preparing meals at home more frequently reduces reliance on higher cost convenience purchases. Similarly, assessing utility consumption helps identify wasteful tendencies, such as leaving electronics plugged in unnecessarily or overusing climate control systems.
Applying Strategic Adjustments to Daily Routines
Practical adjustments can significantly reduce unnecessary spending. One effective approach involves developing a mindful purchasing routine. This does not require rigid constraints; instead, it demands a conscious pause before each expenditure. Asking questions like “Is this necessary?” or “Can I obtain the same result more economically?” encourages evaluative thinking.
Bulk purchasing also provides meaningful advantages, particularly for households consuming staple goods regularly. Items like grains, snacks, toiletries, or cleaning supplies are often available at reduced unit costs when bought in larger quantities. At the same time, it is essential to avoid overbuying perishable goods that may spoil before use. Balancing prudence with practicality ensures these strategies remain effective.
Subscription services represent another area where subtle spending accumulates. Entertainment platforms, specialty apps, digital magazines, and professional tools can easily multiply without consistent monitoring. Conducting a subscription audit every few months helps eliminate redundant or rarely used services. Many individuals are surprised at how much they recover simply by canceling overlooked renewals.
Reducing Transportation and Commuting Costs
Transportation constitutes a substantial portion of daily expenses for many households. Fuel costs, transit fares, vehicle maintenance, and parking fees add up quickly. Evaluating commuting patterns can reveal several opportunities for savings.
For instance, carpooling with coworkers or neighbors divides costs among several individuals. Using public transportation whenever possible provides an economical alternative to solo driving. Even incorporating walking or cycling for shorter distances not only reduces spending but also enhances physical well being.
Maintaining vehicles proactively also mitigates future expenses. Tasks like checking tire pressure, performing scheduled servicing, and monitoring fluid levels extend the life of a vehicle and prevent costly repairs. Small mechanical issues escalate quickly when ignored, turning minor maintenance into major financial setbacks.
Optimizing Household Resource Consumption
Household expenses provide fertile ground for cost reducing tactics. Many utilities fluctuate based on consumption, making awareness a powerful tool. Simple actions, such as adjusting water heater temperatures, sealing drafty windows, and using energy efficient bulbs, decrease monthly bills.
Evaluating internet and mobile phone plans can also uncover opportunities. Service providers frequently offer promotions or alternative plans that better match usage habits. Comparing providers once or twice a year ensures that households are not unknowingly paying premium prices for outdated contracts.
Groceries, a substantial household expense, benefit greatly from structured planning. Crafting weekly meal schedules reduces impulse purchases and minimizes food waste. Comparing store prices or using loyalty rewards creates additional advantages. Even adopting generic brands for certain items can produce consistent savings without sacrificing quality.
Strengthening Financial Discipline Through Mindful Tracking
Tracking expenses remains one of the most effective methods for controlling spending. Whether through a digital budgeting app or a traditional notebook, consistent recording illuminates behavioral patterns. Reviewing this data weekly enables timely course corrections.
This habit also fosters financial accountability. When individuals visually observe their spending trends, they tend to make more thoughtful decisions. The process creates a feedback loop that encourages discipline and discourages impulsive purchases.
Furthermore, integrating periodic financial check ins enhances long term progress. Families can meet monthly to evaluate goals and adjust strategies. This collaborative approach strengthens communication and ensures that everyone contributes to a shared financial vision.
Evaluating the Psychological Factors Behind Spending
Human behavior influences financial decisions more than most people realize. Emotional shopping, convenience routines, and habitual indulgences often lead to overlooked expenses. Recognizing these tendencies provides a foundation for improvement.
One effective method involves identifying personal triggers. Some individuals shop to relieve stress, while others indulge when bored or seeking novelty. Developing alternative coping mechanisms helps break these cycles. Engaging in hobbies, physical activity, or personal projects channels energy productively without incurring costs.
Even subtle mindset shifts can be powerful. Reframing saving as a form of personal empowerment increases motivation. Viewing expenses through a lens of long term benefit rather than immediate gratification strengthens financial resilience.
Implementing Sustainable Long Term Practices
Cutting daily expenses does not require austerity. Instead, it emphasizes optimization, awareness, and thoughtful prioritization. When practiced consistently, these habits create a sustainable financial environment that supports future goals.
Through incremental adjustments, individuals gain greater control over their spending landscape. They cultivate a lifestyle anchored in purposeful choices and balanced resource management.



